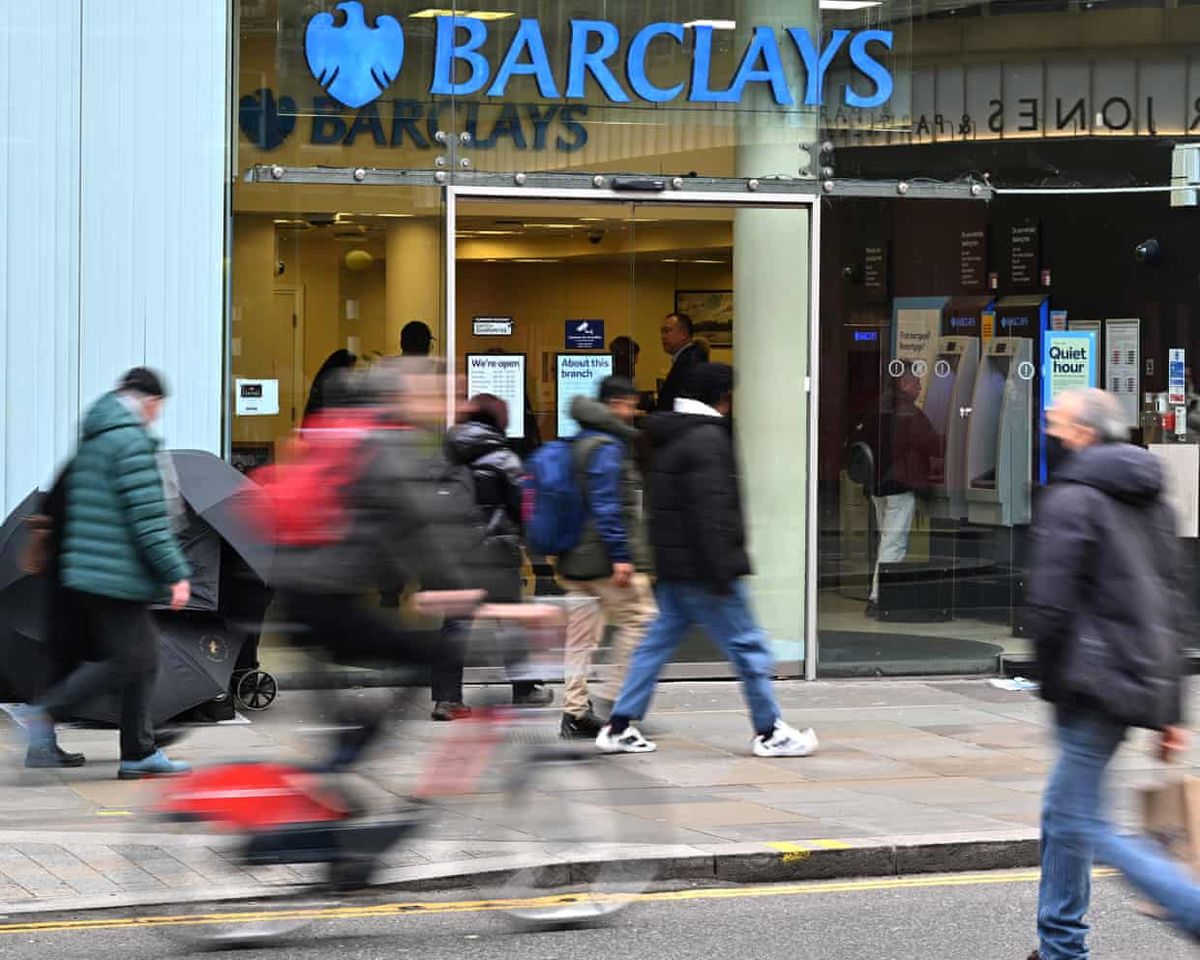
Barclays announced on Thursday that it is cutting 5,000 jobs as part of a wider cost-saving plan driven by advances in artificial intelligence.
The reductions represent about 5% of the bank’s 93,000 global staff members. Executives confirmed they had already removed 1,000 workers since the start of the year.
Chief financial officer Anna Cross told reporters on Thursday that the cuts form part of a strategy to save more than £1.1bn in 2027. She stated that these actions involve an expected reduction of circa 5,000 full-time employees, with around 60% of group actions relating to support functions, including fewer developers, as AI makes people more productive.
When asked how many total cuts linked directly to AI advances, chief executive CS Venkatakrishnan said the bank had been making deep investments in technology and simplifying processes. He called AI the icing on the cake to modernising the bank’s technology.
Sharon Graham, general secretary of the Unite union, said Barclays workers deserved better. She accused the company of using AI as an excuse to discard its loyal and long-suffering workforce, adding that employers should focus on upgrading employee skills rather than taking a short-term, kneejerk approach.
The announcement follows a move months earlier by another UK-headquartered lender, Standard Chartered, which revealed plans to cut more than 7,000 jobs over four years by ramping up AI use.
Barclays also announced plans to hand a further £500m to investors. This brings the total amount given to shareholders through buybacks and dividends since January to £2.8bn.
The lender reported £2.3bn in pre-tax profits over the July to September quarter. That figure is up 12% from £2.1bn during the same period last year.
Venkatakrishnan stated the bank would be able to absorb expected increases in bank taxes in the upcoming budget. He noted that Barclays shared the government’s goal to prompt growth.
Trade unions renewed calls for higher bank taxes amid the strong financial results. TUC general secretary Paul Nowak said Britain’s big four banks have made £200bn in profit since 2021 and should pay more tax while people struggle with household bills.